- Parliament has handed the executive power to introduce a charge without a public cost audit, comparison of funding alternatives, or statutory limits on future expansion. Clear answers are needed on how the system will operate and how it may change later.
- The Centre promises personal transfers and most merchant payments will remain free; any charge will be small and apply only above a threshold. However, these promises are absent from the text of the amended law.
- UPI processed more than 24,000 crore transactions worth Rs 314 lakh crore in 2025-26. A parliamentary committee found that the Rs 8,730 crore subsidy paid between 2021-22 and 2024-25 covered only 11% of the digital-payment industry’s costs.
- In 2025-26, only 4% of merchant UPI transactions exceeded Rs 2,000, but they represented about two-thirds of their total value, making the missing rules particularly important.
- Charging merchants does not guarantee that citizens will pay nothing, as businesses can include the fee in prices. If digital payments become more expensive, some consumers and businesses may return to cash, weakening financial inclusion and undermining policy gains.
- A modest fee on large businesses could finance secure infrastructure, but a merchant fee might not be the most obvious or fairest solution. UPI saves the State money, brings transactions into the formal economy, improves tax compliance, and gives millions access to convenient payments.
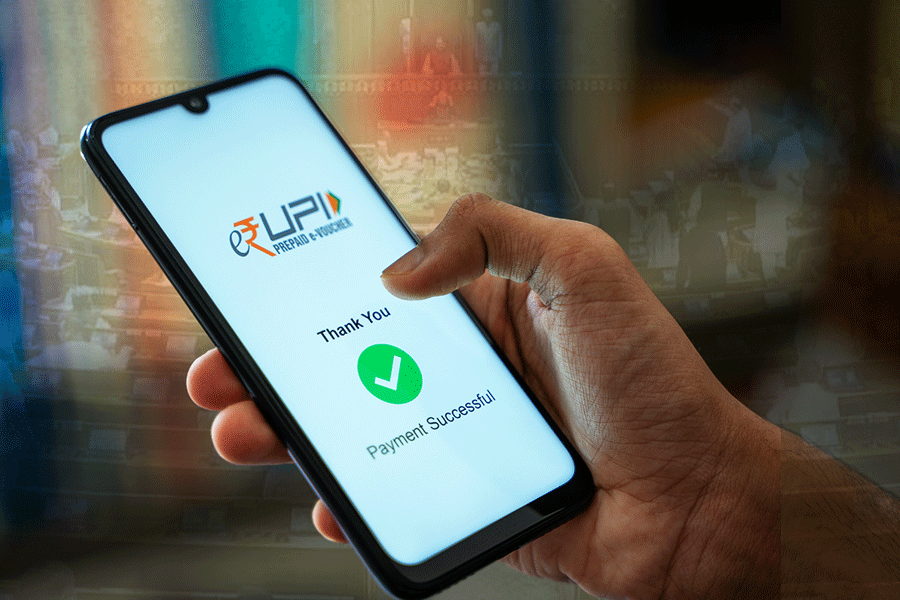
Parliament's recent passage of the Taxation and Other Laws (Amendment) Bill, 2026 has sparked significant debate regarding the future of UPI financing. The bill grants the government authority to impose charges on UPI transactions, a move that could alter the landscape of digital payments in India.
The Centre assures that personal transfers and most merchant payments will remain free, with any potential charges being minimal and applicable only above a certain threshold. However, these assurances are notably absent from the bill's text, leaving many questions unanswered regarding the specific rates, payment limits, and safeguards against costs being passed to consumers.
In the fiscal year 2025-26, UPI processed over 24,000 crore transactions worth ₹314 lakh crore, highlighting its significance in the digital payment ecosystem. Despite a parliamentary committee revealing that the ₹8,730 crore subsidy from 2021-22 to 2024-25 covered only 11% of the industry's costs, the government is considering a modest fee on large businesses to finance secure infrastructure.6
Critics argue that charging merchants could lead to increased costs for consumers, as businesses might incorporate these fees into their pricing. This could deter users from digital payments, potentially reversing the progress made in financial inclusion and economic activity recording. In 2025-26, only 4% of merchant UPI transactions exceeded ₹2,000, yet they accounted for two-thirds of the total value, underscoring the need for clear regulations.4
The lack of a public cost audit and statutory limits on future charges raises concerns about transparency and accountability. As UPI's financing model evolves, thorough scrutiny is essential to ensure that the benefits of digital payments are not undermined by hidden costs.
“In 2025-26, only 4% of merchant UPI transactions exceeded ₹2,000, yet they accounted for about two-thirds of total value, making the missing rules critical. A parliamentary committee found the ₹8,730 crore subsidy covered just 11% of industry costs, raising concerns about cost pass-through to consumers.”