- India has successfully raised $50 billion from the diaspora through FCNR deposits.
- The RBI has advanced the FCNR deposit deadline to August 31, indicating that the response has exceeded the central bank's estimates.
- The RBI has also decided to end the swap facility early, which is unlikely to impact the rupee significantly.
- The inflows provide an additional buffer for the central bank as elevated crude oil prices put pressure on the rupee.
- India's bond market might see a selloff, especially at the shorter end, when trading resumes, as excess cash was being parked in bonds.
- Rajeev Pawar, head of treasury at Ujjivan Small Finance Bank, noted that the premature close of the deposit plan makes the view on liquidity less favorable.
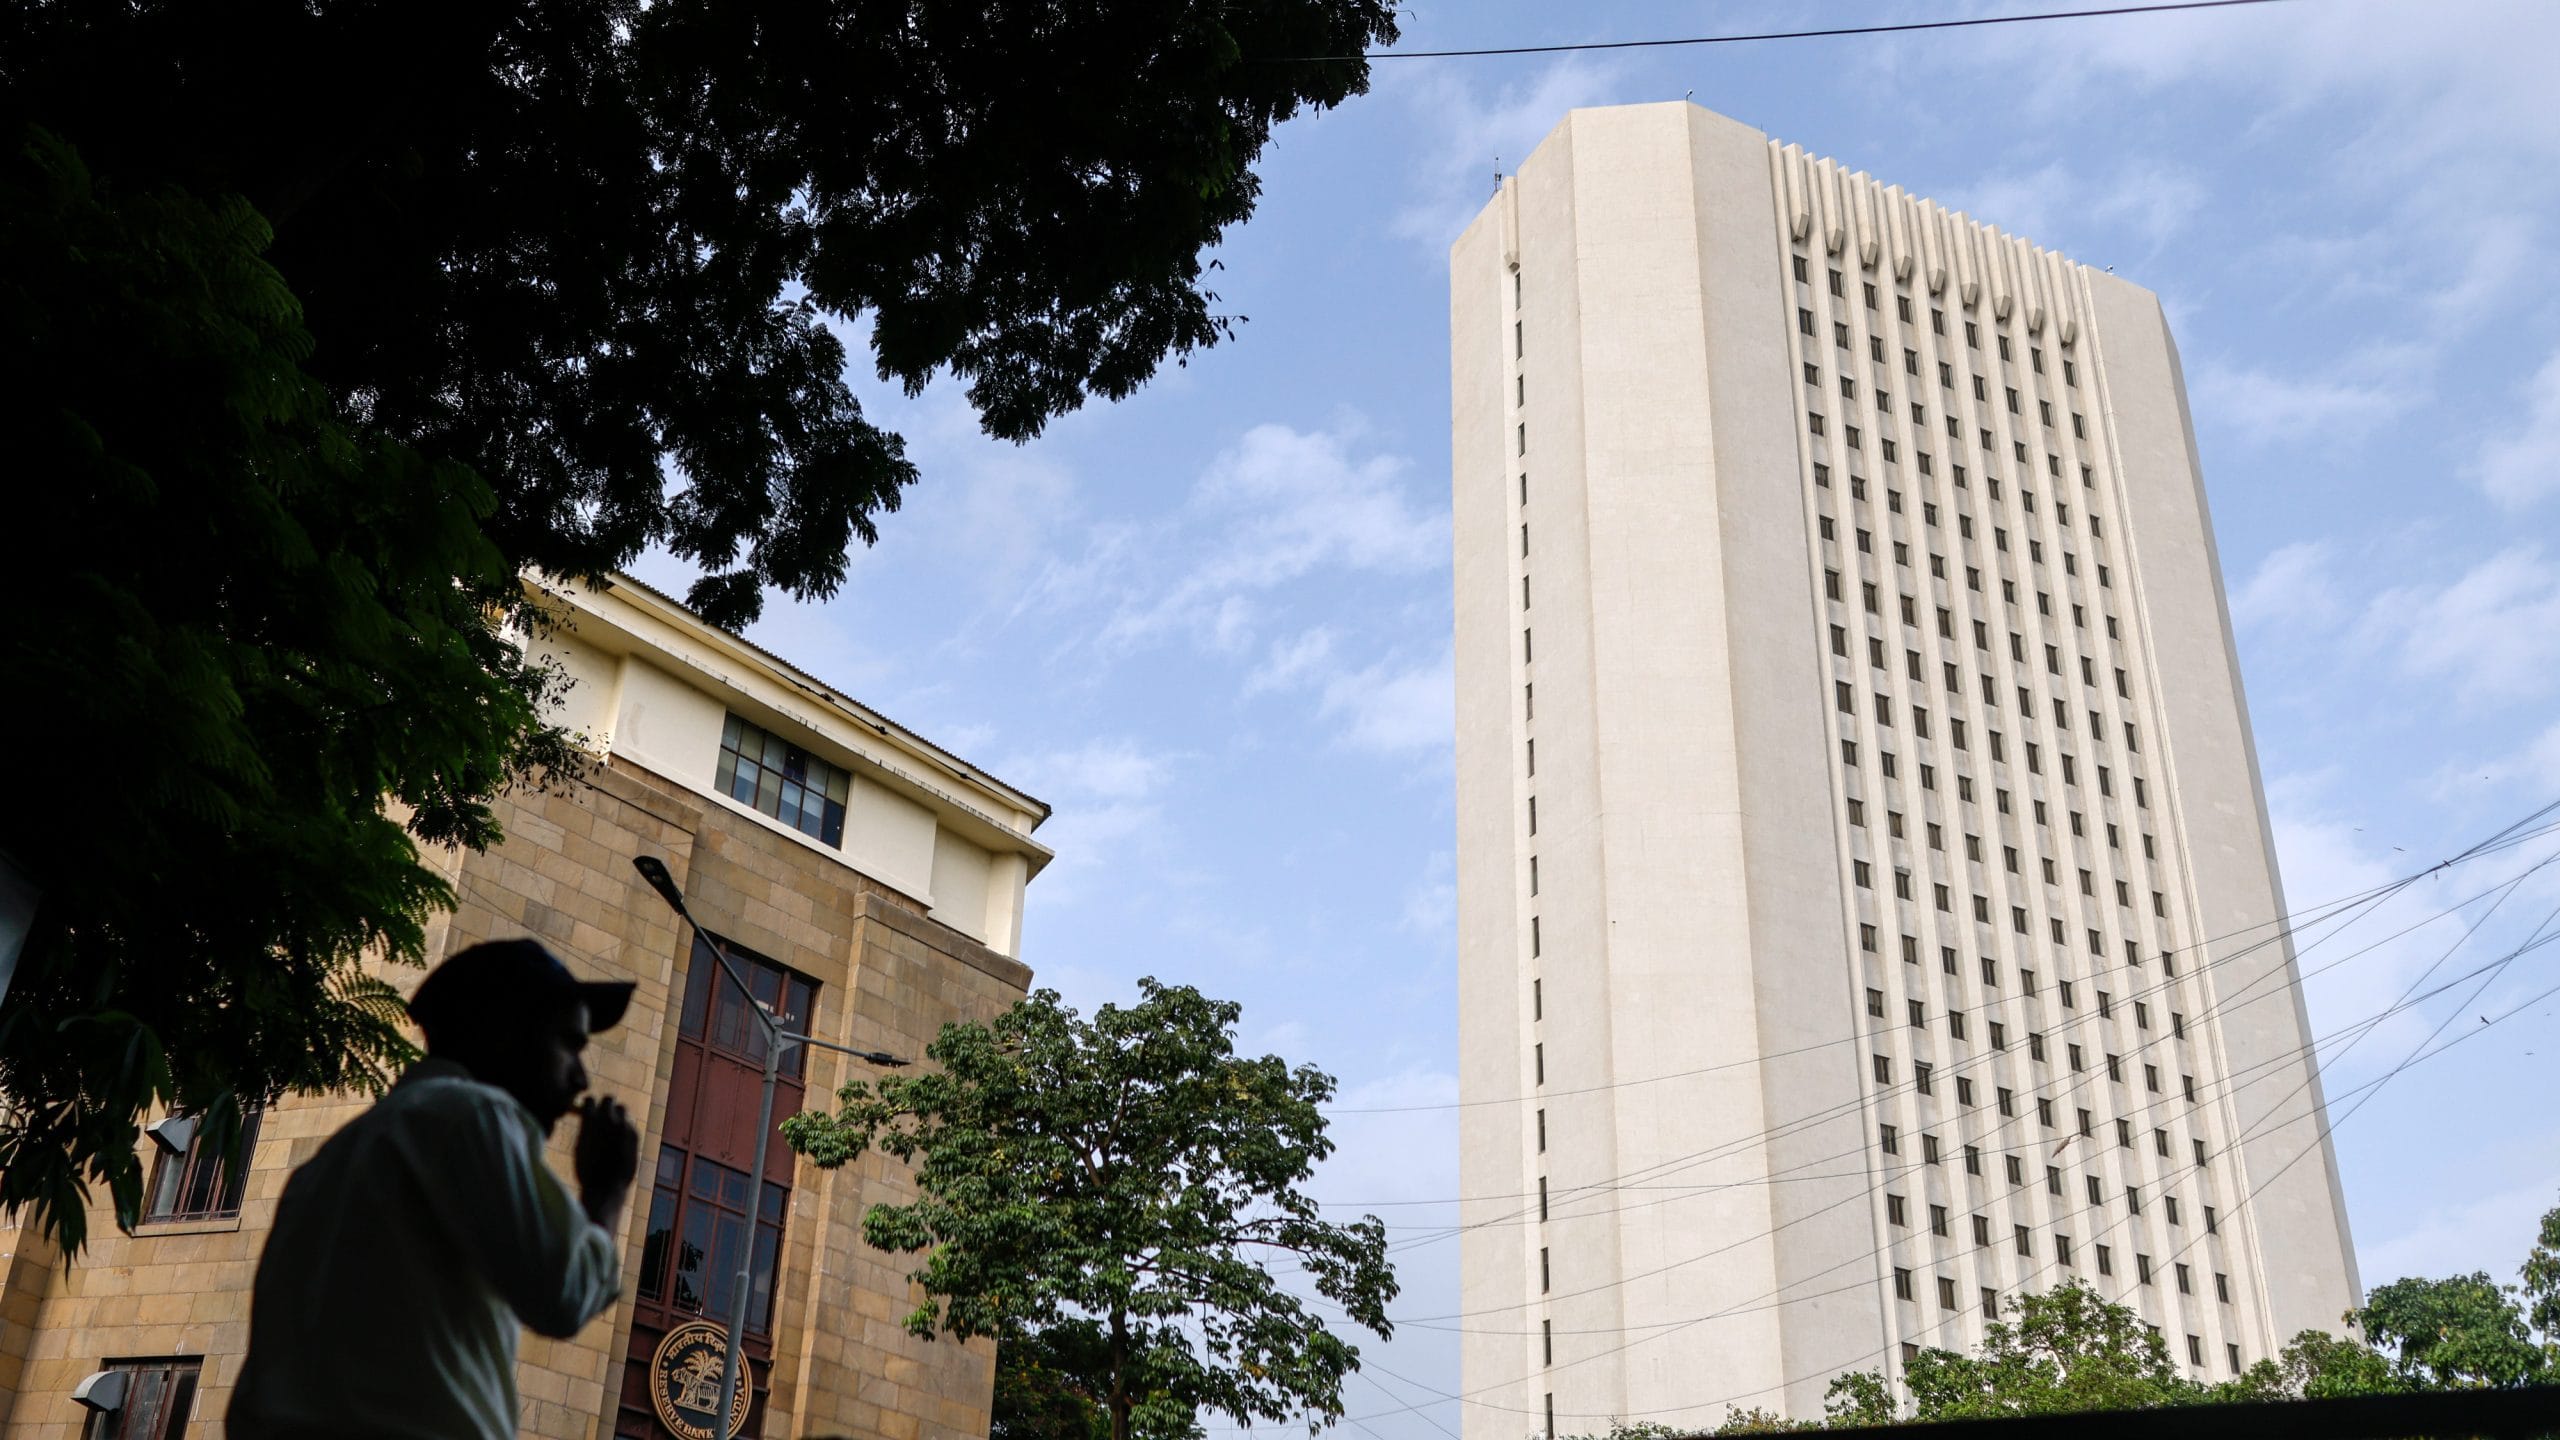
India has successfully attracted over $50 billion from its diaspora since June, leading the Reserve Bank of India (RBI) to close its foreign-currency deposit facility a month early, on August 31. This decision follows a remarkable inflow of $52.3 billion into FCNR(B) deposits, which has significantly bolstered foreign-exchange reserves amid ongoing pressure on the rupee.12
The RBI's early closure of the facility indicates that the response has surpassed expectations. Gaura Sen Gupta, chief economist at IDFC FIRST Bank Ltd, noted that total inflows under the program are still projected to reach $70 billion. The central bank had previously announced it would cover currency-hedging costs for lenders raising deposits from overseas Indians, further incentivizing banks to attract capital from the country's 35 million-strong diaspora.
With banks offering interest rates as high as 7.75% on five-year deposits, the competition for these funds has intensified. The inflows are crucial for the RBI, providing a buffer against elevated crude oil prices that are exerting pressure on the rupee. However, the early closing of the swap window is not expected to significantly impact the rupee, as the program has already generated substantial overseas flows.4
Market analysts suggest that the premature closure may lead to a selloff in India's bond market, particularly at the shorter end, as Rajeev Pawar, head of treasury at Ujjivan Small Finance Bank, remarked, “Excess cash was being parked in bonds, especially the short end.”
“Total inflows, including overseas foreign currency loans and external commercial borrowings, reached $56.85 billion, with expectations of $70 billion. The early closing may trigger a bond market selloff at the short end, as excess cash parked in bonds gets withdrawn.”